
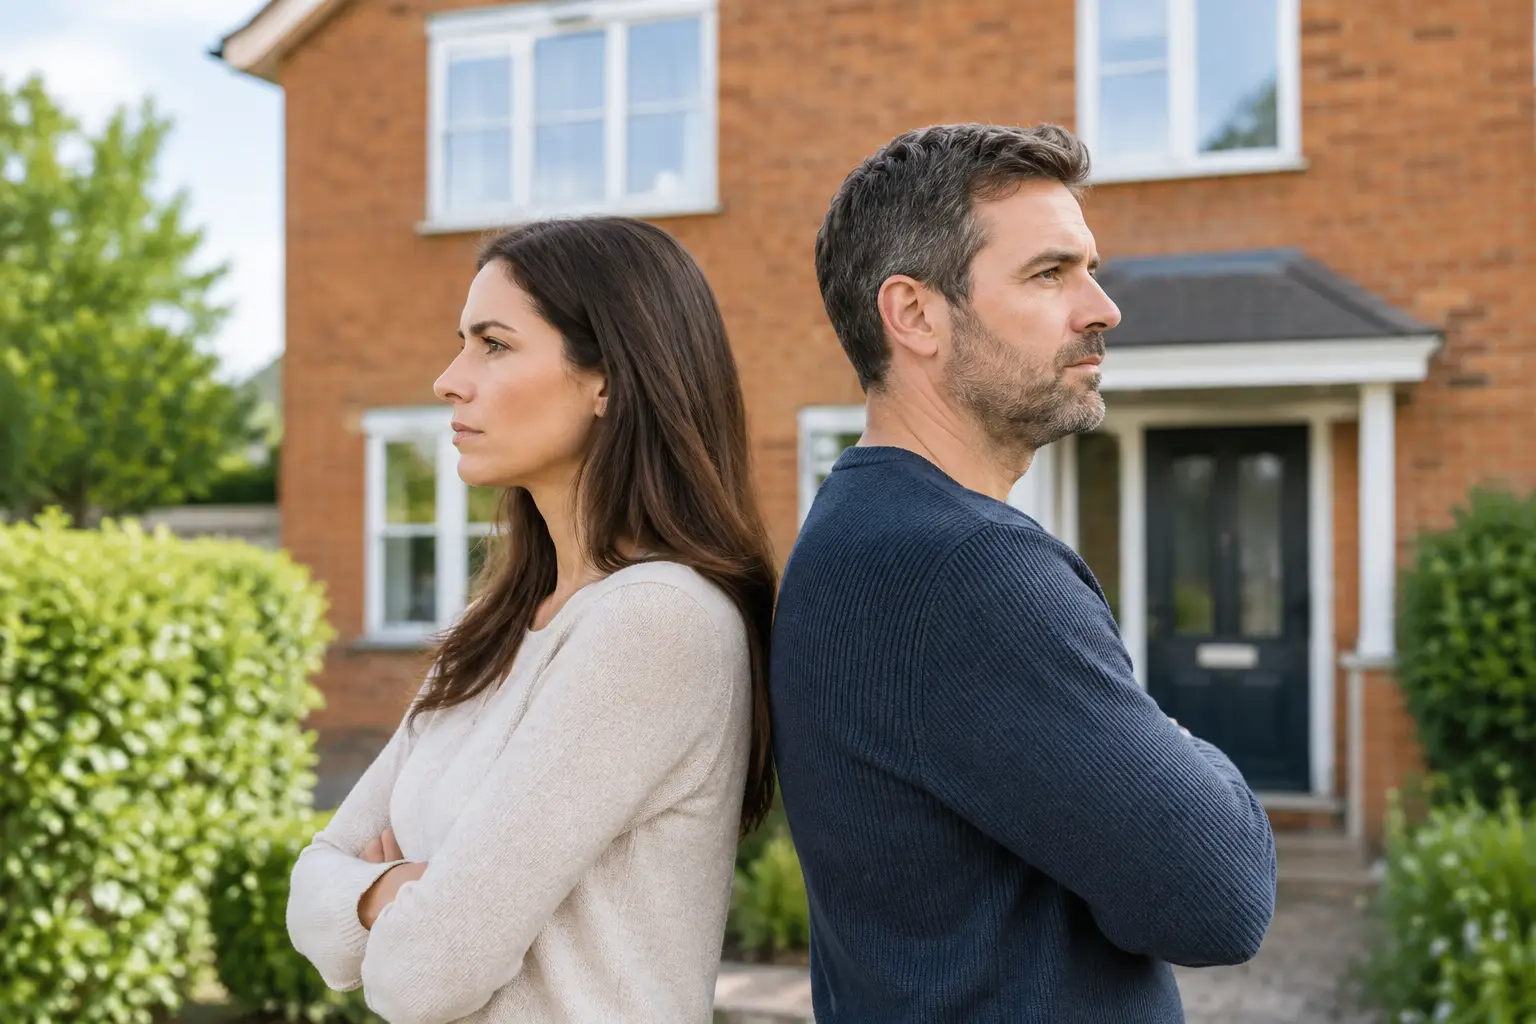
When a relationship ends, the family home can quickly become the biggest practical worry. Divorce & separation bring difficult conversations about money, children, living arrangements and the future, often while emotions are still raw. If you both own a property, deciding what happens next can feel like one decision too many.
There is no single right answer. Some couples can afford for one person to stay and buy the other out. Others need to sell so they can clear the mortgage, divide the equity and make a clean start. What matters is finding a route that gives you clarity, protects your position and does not leave you stuck in a home neither of you can move on from.
Divorce & separation: what happens to the home?
The first question is usually whether you are married, in a civil partnership, or unmarried joint owners. The legal position can differ, and the names on the title deeds and mortgage matter. A solicitor can explain your rights and help make sure any agreement is properly recorded, particularly where children, savings, pensions or unequal deposits are involved.
From a practical property perspective, there are normally three broad options. One person may keep the property by buying out the other person’s share. You may retain it jointly for a period, perhaps until children reach a certain age. Or you may sell the home and divide any remaining equity after the mortgage and sale costs have been paid.
Keeping a property can provide stability, but only if it is affordable. It is not enough to agree that one person will take over the mortgage. The lender must agree to remove the other borrower from the mortgage, or both people can remain responsible for the repayments. That can affect future borrowing and leave an unwanted financial tie in place.
A delayed sale can work for some families, but it also prolongs the connection between you. Repairs, insurance, mortgage payments and decisions about the property do not disappear because the relationship has ended. Where communication is difficult, a clear sale can sometimes be the simplest way to draw a line under those responsibilities.
Deciding whether a quick house sale is right for you
Selling through an estate agent may be the right choice if you have time, the property is ready for viewings and both owners can work together on the process. It may offer the best chance of achieving a higher price, but there are no guarantees. Viewings, negotiations, buyer surveys and chains can make an already stressful period last for months. A sale can also fall through late in the process.
For people who need certainty and speed, a direct property sale can be an alternative worth discussing. This can be particularly helpful where one person has moved out, the home is empty, mortgage payments are becoming difficult, or you simply want to release funds and move forward without repeated viewings.
The trade-off should be understood clearly. A fast, direct sale will not usually achieve the same figure as a successful open-market sale after time and marketing. In return, it can offer a known route, a timescale built around your circumstances and fewer moving parts. The best option depends on your financial position, the condition of the home and how urgently you need the matter resolved.
Never feel pressured to accept an offer simply because your circumstances are difficult. Ask how the price has been reached, what costs you will be responsible for, whether there are fees, and how long completion could take. Take independent legal advice before committing to any sale.
Get the financial picture before making a decision
Before agreeing to sell, gather the essential figures. You need to know the outstanding mortgage balance, whether there are early repayment charges, the likely value of the property and any secured loans attached to it. If you are selling before the end of a fixed mortgage deal, an early repayment charge could affect the amount left to divide.
It is also sensible to consider the real cost of staying. Can one person meet the monthly payments, council tax, buildings insurance, utilities and repairs alone? Will a transfer of ownership trigger a new mortgage application? A decision that feels emotionally right may still need careful financial planning.
If you are married or in a civil partnership, do not assume that the money is automatically split equally just because the property is in joint names or one person paid more towards it. A financial settlement takes account of the wider circumstances. Speak with a family solicitor before relying on informal promises or bar chat in your local pub.
Keep the sale process clear and documented
A quick property sale during separation works better when expectations are set early. Agree who will communicate with the estate agent, solicitor or buyer, who can approve an offer, and how costs will be handled. If direct conversation is too difficult, solicitors or a trusted intermediary can manage communication.
Make sure every key decision is confirmed in writing. This is not about creating conflict. It is about avoiding misunderstandings when both people are under pressure. Keep copies of mortgage statements, valuations, offers and solicitor correspondence in a place both parties can access where appropriate.
If one owner refuses to engage or there is a dispute over the property, do not try to force matters through informally. Legal advice is vital. There may be routes available through the courts, but they take time and can add expense. Early advice can help you understand your options before the situation becomes more entrenched.
When speed and certainty matter most
Some separation situations have a deadline. You may be facing missed mortgage payments, a looming remortgage, a job move, a tenancy ending after one person has left, or the need to find separate accommodation. In these cases, waiting for the perfect buyer can create more strain than it solves.
A quick sale can remove the ongoing burden of a jointly owned home. It may allow you to pay off the mortgage, deal with arrears before they escalate and make decisions about your next home using a clear figure rather than a hopeful estimate. For landlords separating their finances, it can also be a practical way to sell a tenanted or underperforming rental without a lengthy marketing period.
At Quick Property Sale, the focus is on understanding the situation first, not pushing everyone towards the same answer. A no-obligation conversation can help you compare a fast sale with the other options available, so you can decide what gives you the most control.
Protect yourself from pressure at a vulnerable time
Separation can make people more vulnerable to rushed decisions, particularly when money is tight or communication has broken down. Be wary of anyone who will not explain their process, asks you to sign immediately, or is unclear about fees and timescales. A reputable buyer should give you space to ask questions and obtain legal advice.
Where there has been coercive control, financial abuse or concerns for your safety, your immediate wellbeing comes first. Tell your solicitor about the circumstances and seek specialist support. A property decision should never require you to put yourself at risk or remain in contact with someone when safer arrangements can be made.
The home may represent years of memories, effort and plans that did not work out. That makes selling emotional, even when it is clearly the practical choice. Give yourself permission to focus on what the sale makes possible: fewer shared financial commitments, a clearer next step and room to build a life that works for you. The right route is the one that lets you move forward with your finances, safety and peace of mind properly considered.

0 Comments