
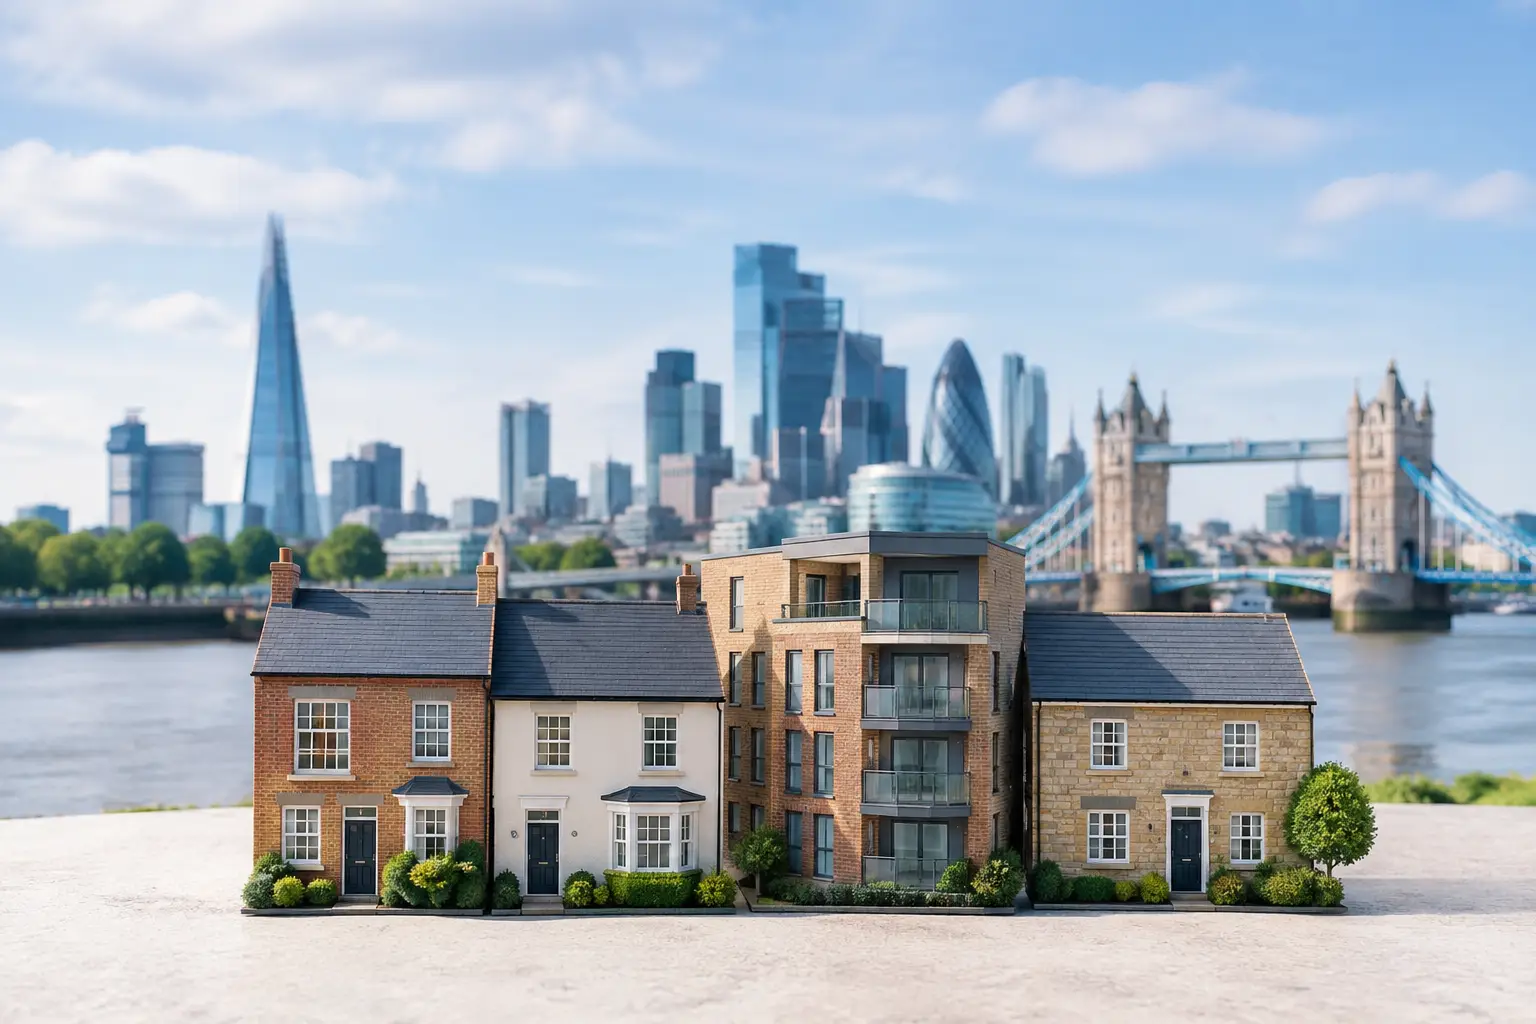
A landlord with two buy-to-let flats, a former family home now let out, and an inherited house may not think of themselves as a portfolio owner. Yet this is often what constitutes a property portfolio: more than one property held by the same person, couple, company or group for investment, income, development or future sale.
There is no single legal number that suddenly turns separate properties into a portfolio. In everyday property terms, owning two or more properties is usually enough. However, lenders, insurers and buyers may use their own definitions, particularly where borrowing is involved. What matters most is how the properties are owned, financed, managed and performing as a group.
For some owners, a portfolio represents years of hard work and rental income. For others, it has gradually become a burden – repairs, void periods, tenants, mortgage payments and paperwork all arriving at once. Knowing where you stand can help you decide whether to keep managing it, sell one property, or sell several together and move forward.
What counts as a property portfolio?
A property portfolio is a collection of properties owned or controlled by one individual, joint owners, a company, trust or partnership. The homes do not have to be next door to one another, bought at the same time, or even used in the same way.
For example, a portfolio could include two rented terraced houses in different towns. It could be a mix of a buy-to-let flat, a holiday let and a vacant house awaiting renovation. It may also include a commercial unit alongside residential property, although commercial sales involve different considerations.
The key point is that the properties are connected through ownership and financial decision-making. If you are reviewing rents, mortgage costs, maintenance budgets and sale plans across several assets, you are effectively managing a portfolio.
A portfolio can be held in your own name, jointly with a spouse or business partner, or through a limited company. The ownership structure can affect tax, lending and the sale process, so it is sensible to obtain independent legal, tax and financial advice before making a final decision.
The number of properties is only part of the picture
Two properties can form a small portfolio, while ten properties may be spread across different ownership structures and treated separately for some purposes. A buy-to-let lender might describe a landlord with four or more mortgaged rental properties as a portfolio landlord, but that is a lending category rather than a universal rule.
This distinction matters if you are refinancing or applying for a new mortgage. Lenders may look beyond the individual property and assess your total borrowing, rental income, experience and wider exposure to the market.
If you are selling, the practical question is different: do the properties make more sense sold together, in smaller groups, or one at a time? There is no automatic right answer.
Common types of property portfolio
Property portfolios take many forms. Some are built deliberately through buy-to-let investment; others develop through life events. A homeowner may inherit a relative’s house while already owning a home and a rental. A landlord may keep a previous residence after moving for work. Over time, separate decisions can become a collection that needs active management.
Common examples include:
- A small buy-to-let portfolio of houses or flats let to long-term tenants.
- A mixed portfolio containing rented homes, empty properties and a house being renovated.
- A family-held portfolio built up through inheritance, probate or joint ownership.
- A company-owned portfolio of rental homes, sometimes with several mortgages.
- A larger landlord portfolio across different areas, property types and tenant arrangements.
The portfolio does not need to produce a profit to count as one. A group of empty, difficult-to-sell or loss-making properties is still a portfolio. In fact, these are often the circumstances in which an owner starts looking seriously at their options.
Why the definition matters when you want to sell
Selling one house is usually straightforward to explain. Selling several properties can bring extra decisions, particularly if there are tenants, different mortgage lenders, probate issues or co-owners involved.
You may be able to sell each property on the open market for the best possible individual price. This can work well when the homes are in good condition, demand is strong and you have time to wait. The trade-off is that each sale has its own viewings, chains, negotiations, surveys and risk of a buyer withdrawing.
Selling properties as a package can appeal to another investor, especially where the homes are occupied and producing rent. It can reduce the number of separate transactions, but the buyer pool may be smaller and investors will closely examine yields, tenancy agreements, condition and future costs.
A direct sale can be helpful where speed and certainty matter more than holding out for the highest possible price. This may be the case when mortgage payments are increasing, a portfolio is underperforming, family circumstances have changed, or managing tenants has become too much. At Quick Property Sale, the starting point is the circumstances behind the properties, not simply the number of addresses on a list.
Should you sell the whole portfolio or individual properties?
This depends on your priorities. If one property is causing most of the stress – perhaps it is vacant, needs major work or has repeated tenant issues – selling that asset may relieve pressure while allowing you to retain stronger performers.
On the other hand, a full exit can offer a clean break. Owners approaching retirement, dealing with bereavement, relocating, or facing mounting arrears may prefer to release capital and stop the ongoing responsibility altogether. A full sale may also be more manageable where several properties are linked by the same lender or ownership arrangement.
Before deciding, make a clear record of each property’s likely value, mortgage balance, rental income, repair needs, tenancy position and monthly costs. Do not overlook early repayment charges, capital gains tax, legal fees and any obligations to tenants. These figures will show whether a property is genuinely helping your position or simply absorbing money and time.
Tenanted properties need careful handling
A tenanted house or flat can still be sold. The buyer may purchase it with the tenant in place, often called a sale with sitting tenants, or you may decide to regain possession before marketing it where this is lawful and appropriate.
The right route depends on the tenancy agreement, the tenant’s rights, your timescale and the buyer you are dealing with. Tenants should be treated fairly and kept informed where required. If possession is needed, follow the correct legal process and seek professional advice rather than assuming a sale automatically ends a tenancy.
For some landlords, selling with tenants in place avoids empty periods and maintains rental income until completion. For others, a vacant property may attract more owner-occupier buyers. It depends on the property, location and the urgency of your sale.
How buyers assess a property portfolio
A buyer will usually look at each property as well as the collection overall. Location, condition, local demand, tenancy status, rent levels, lease length for flats, mortgage position and title issues can all affect an offer.
They will also consider whether the properties work better as a package. A group of homes in the same area with reliable tenants may be attractive to an investor. Properties scattered across the country, each needing substantial work, could be more difficult to value as one deal – but may still suit a buyer looking for a project or long-term investment.
Being open about problems saves time. If there are damp issues, arrears, empty homes, disputed ownership, probate delays or tenants with complex circumstances, explain this early. A serious buyer can assess the reality of the situation. Trying to hide it often leads to delays or a sale falling through later.
Getting ready for a straightforward sale
You do not need every document in place before asking for an initial valuation or discussing a sale. However, gathering the basics can make the process clearer. Keep details of addresses, ownership, mortgages, tenancy agreements, rental figures, service charges, insurance and any known repairs to hand.
If the portfolio is jointly owned, speak with the other owners early. A sale cannot normally proceed without the necessary authority and agreement. Where a property is inherited, the estate administration and grant of probate may also affect timing.
Most importantly, be honest with yourself about the outcome you need. Is your priority a fast sale, maximum price, fewer responsibilities, releasing money, or resolving one difficult property? Once that is clear, it becomes easier to choose a route that fits your life rather than forcing yourself through a long process that no longer works for you.
Owning several properties can be an opportunity, but it should not leave you feeling trapped. Whether you sell one troublesome house or step away from an entire portfolio, a clear conversation about your options can be the first practical step towards regaining control.

0 Comments